Call Us Now
 Email Us Now

Imagine inheriting a cottage on one of Michigan’s beautiful lakes.
It’s the place where your family spent summers. Where you learned to swim, celebrated birthdays, and watched the sun go down from the dock. Your parents loved it, and now they’ve left it to you and your siblings.
What a wonderful gift.
Until the bills start arriving.
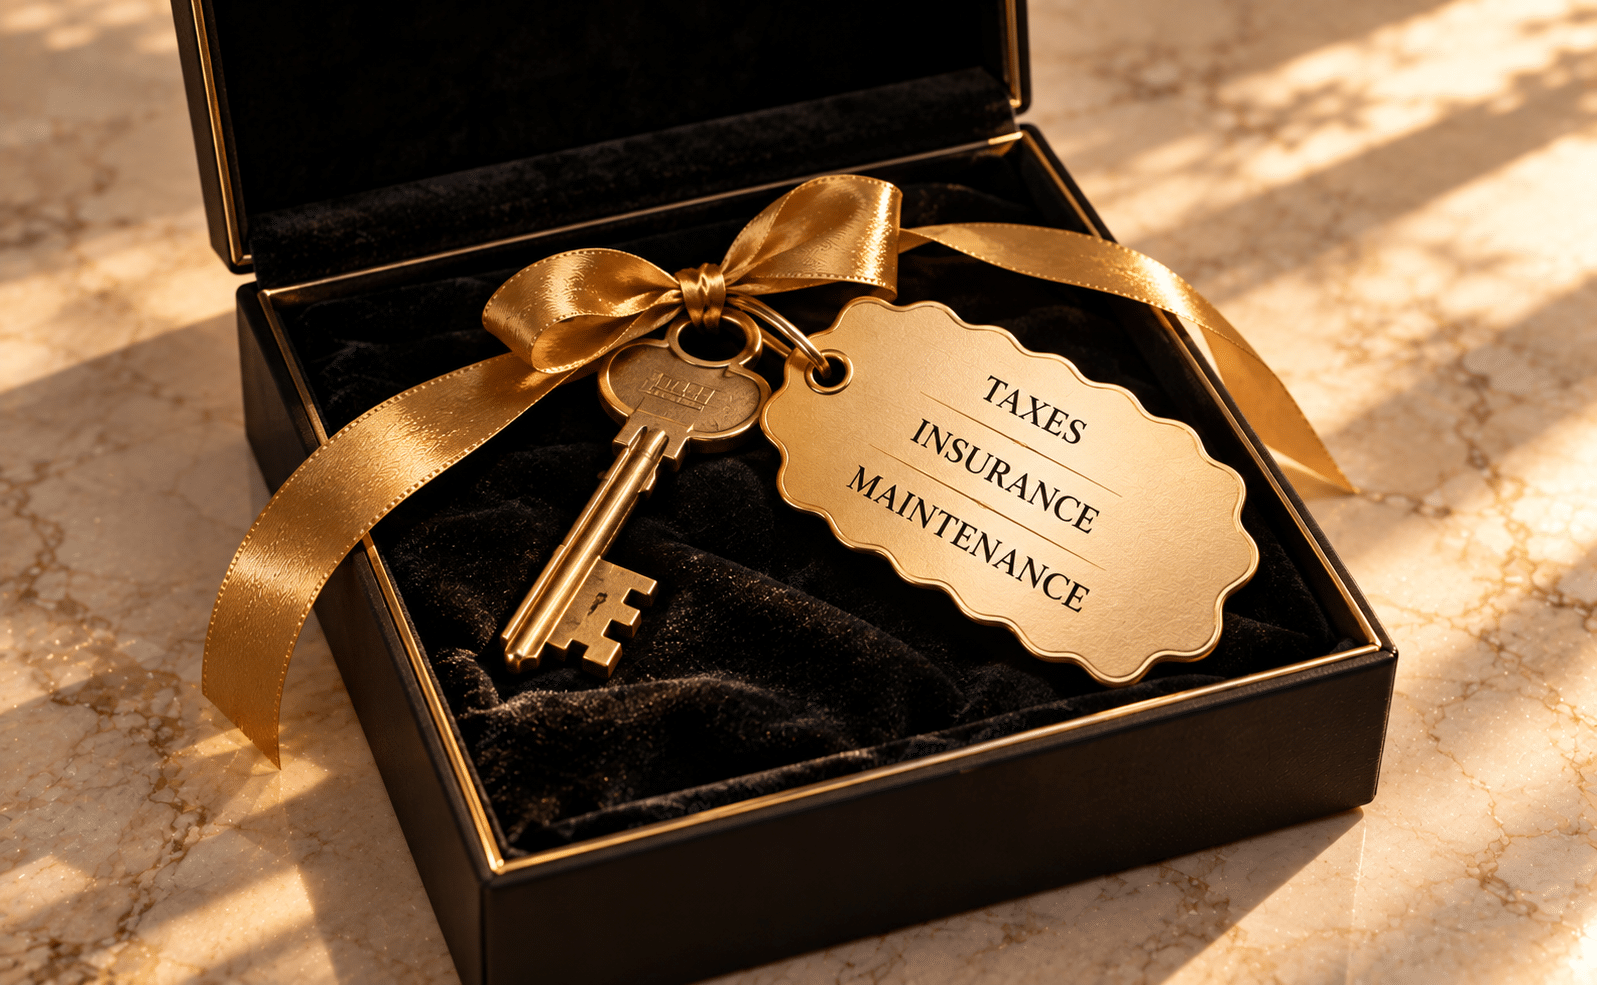
Property taxes. Insurance. Repairs to an aging roof. The dock that needs replacing. The heating system that wasn’t designed for another Michigan winter.
Then come the conversations.
One sibling wants to keep the cottage forever. Another one lives out of state and would rather sell. A third wants to rent it out, but nobody agrees on who should manage the property or how the income should be divided.
Suddenly, what was meant to be a generous inheritance has become a source of expense, disagreement, and uncertainty.
But what if those questions had been addressed before the cottage was inherited?
What if the parents had discussed whether their children actually wanted to own the property together? What if their estate plan established a process for one sibling to purchase the others’ interests, or provided clear instructions for how the property should be managed or sold?
The family might still face difficult decisions. But they wouldn’t necessarily be starting from scratch.
This is one of the most important things estate planning can do: anticipate problems before they become someone else’s responsibility.
THE INHERITANCE IS ONLY HALF THE PLAN
Who gets the house? Who inherits the savings? Who receives the family cottage?
Those questions matter. But they are only part of the conversation.
A well-considered estate plan also looks at what happens after ownership changes.
Will the beneficiaries be able to manage what they inherit? Could the transfer create unexpected expenses or disagreements? Are there special circumstances that require a different approach? And are the right legal arrangements in place to carry out the owner’s intentions?
These are questions worth discussing while the person making the plan can still make decisions about them.
For example, parents who want to leave a vacation property to several children may benefit from discussing whether a trust or another arrangement could establish a process for managing, maintaining, or eventually selling the property.
Someone leaving assets to a loved one who receives means-tested government benefits may need to consider whether a special needs trust is appropriate.
And a person with retirement accounts or life insurance policies should make sure beneficiary designations are coordinated with the rest of the estate plan.
These situations may call for different solutions, but they share an important consideration: an inheritance needs to work for the people receiving it.
WHEN A GIFT COMES WITH A BILL
A house worth $350,000 sounds like a substantial inheritance.
But what if the person receiving it cannot afford to keep it?
Property taxes, insurance, utilities, maintenance, and repairs continue long after ownership changes. A family cottage may require seasonal upkeep. An older home could need significant work before anyone can live in it or sell it.
In Michigan, inherited property can also raise questions about property tax assessments. Depending on the circumstances, a transfer of ownership may affect a property’s taxable value, although certain transfers may qualify for exceptions under state law.
For someone who has owned a property for decades, the annual expenses may seem routine. For a beneficiary managing their own mortgage, family expenses, and financial obligations, those same costs can be difficult to absorb.
This is why planning for real estate should involve more than identifying who receives the deed.
It may be worth considering whether the intended beneficiary wants the property, whether they can reasonably maintain it, and what alternatives might better serve everyone involved.
Sometimes keeping a home in the family is exactly what everyone wants. Other times, the more thoughtful gift may be the proceeds from its sale.
WHEN EVERYONE INHERITS TOGETHER
Leaving a property equally to several children can feel like the fairest approach.
But equal ownership doesn’t necessarily mean equal interest, equal financial ability, or equal willingness to manage the property.
One sibling may want to live there. Another may need the proceeds from a sale. Someone else may want to preserve it for future generations.
Who pays the bills while everyone decides? Who approves repairs? Can one sibling buy out the others? What happens if they cannot agree?
Depending on how the property is owned and the circumstances involved, disagreements may eventually require legal action, including a possible partition proceeding.
These disputes don’t always begin with resentment or bad relationships. Sometimes they arise because nobody established a workable process for making decisions.
An estate plan can address some of these concerns in advance.
For example, a trust or other appropriately structured arrangement may establish how a property will be managed, whether a beneficiary has an opportunity to purchase it, or under what circumstances it should be sold.
The right approach depends on the family’s goals and the legal and practical considerations involved.
NOT EVERY INHERITANCE IS EASY TO MANAGE
Money in a bank account is one thing.
A family business, valuable collection, or retirement account can be quite another.
A business may require someone to manage employees, contracts, expenses, and daily operations. A collection of antiques or other valuables may need professional appraisal, insurance, storage, or a specialized buyer.
Even an asset with considerable value may not provide money that a beneficiary can readily use.
Retirement accounts bring their own considerations. Depending on the type of account and the beneficiary’s circumstances, inherited retirement assets may be subject to distribution requirements and tax consequences.
These differences matter when deciding how assets should be distributed.
For example, leaving a business equally to children who have very different levels of involvement may create practical difficulties. One may have spent years helping operate it, while another has no interest in participating.
A thoughtful plan can consider those differences rather than assuming that dividing every asset equally will always produce the most workable result.
WHEN AN INHERITANCE AFFECTS GOVERNMENT BENEFITS
An inheritance can create an especially complicated situation when the beneficiary receives means-tested government assistance.
Some individuals rely on Supplemental Security Income (SSI), Medicaid, or other programs with financial eligibility requirements.
Depending on the benefit program and the individual’s circumstances, receiving assets outright may affect eligibility.
That creates a difficult possibility: money intended to improve someone’s financial security could also change the assistance they depend on.
In appropriate circumstances, a special needs trust may allow assets to be set aside for a person with a disability while accounting for applicable benefit rules.
Michigan’s MiABLE program may also be relevant for eligible individuals. MiABLE accounts allow qualifying people with disabilities to save for certain expenses under special tax and public-benefit rules.
A special needs trust and a MiABLE account serve different purposes, and neither is appropriate in every situation.
The broader lesson is that an inheritance should account for the beneficiary’s circumstances. A distribution that works well for one family member may require a different structure for another.
THE BENEFICIARY DESIGNATION PLOT TWIST
Sometimes the surprise isn’t what someone inherits.
It’s who receives it.
A person may update a will or trust after getting married, divorced, or welcoming a child, but forget about the beneficiary designations attached to retirement accounts or life insurance policies.
Those designations often control how the assets pass, independently of the instructions in a will.
Imagine someone who carefully revises their estate planning documents to provide for a current spouse but leaves an outdated beneficiary designation on an account opened many years earlier.
Depending on the account, applicable law, and plan documents, the result may be different from what that person intended.
Certain retirement plans are also subject to federal rules that can affect beneficiary rights and distributions.
This is why beneficiary designations deserve attention whenever an estate plan is created or reviewed.
A will, trust, insurance policy, retirement account, and property ownership arrangement should not be treated as unrelated pieces of paperwork.
They may operate differently under the law, but they all influence what happens to a person’s assets.
And sometimes, the smallest overlooked detail creates the biggest surprise.
CAN SOMEONE SAY NO TO AN INHERITANCE?
Not everyone wants or is prepared to accept what they’ve been left.
A beneficiary may have financial concerns, personal reasons, or other circumstances that make accepting an inheritance undesirable.
Under certain conditions, Michigan law allows a person to disclaim an interest in inherited property.
A disclaimer is a formal legal refusal to accept that interest.
But it is not necessarily as simple as declining a gift.
The form, timing, and legal consequences matter. Federal tax rules may impose additional requirements, and a disclaimer can affect who receives the property instead.
A person generally cannot assume they can accept the benefits of an inheritance, later decide against it, and still obtain the same legal result.
Disclaimers can be useful in appropriate circumstances, but they are not a substitute for considering the beneficiary’s needs and preferences before the inheritance is made.
In many cases, an earlier conversation could reveal that someone never wanted the property in the first place.
A BETTER GIFT BEGINS WITH BETTER QUESTIONS
There is nothing wrong with wanting to leave someone a family home, a business, a cherished collection, or financial resources.
Those gifts may carry enormous personal meaning.
But meaningful gifts deserve practical consideration, too.
Does the person actually want the asset? Can they afford to maintain it? Will they need to make decisions with other beneficiaries? Could receiving it affect their financial or legal circumstances? Is someone prepared to manage it if necessary?
The answers may influence how an estate plan is structured.
They may also lead to conversations families have been putting off.
A parent might discover that none of their children wants the family cottage. A grandparent might learn that leaving money outright to a grandchild with a disability could create complications. A business owner might realize that the person most interested in continuing the business is not necessarily the person best positioned to manage its financial responsibilities.
These aren’t reasons to abandon generous intentions.
They’re reasons to make those intentions more thoughtful.
NO TRICKS. JUST THOUGHTFUL PLANNING.
An inheritance isn’t measured only by what an asset is worth. It also matters whether the gift makes sense for the person receiving it.
The best estate plans cannot anticipate every change or prevent every disagreement. But they can address foreseeable questions, establish clearer arrangements, and give families a better starting point.
And that’s worth considering long before anyone has to make those decisions.
Because the best treats are the ones that don’t leave your loved ones dealing with unexpected tricks.
Estate Planning & Elder Law Services, P.C. helps Michigan individuals and families consider how their assets will be transferred and how their estate planning decisions may affect the people they love.
To discuss your estate planning needs, call (888) PLAN-050, email info@formyplan.com, or visit formyplan.com.