Call Us Now
 Email Us Now

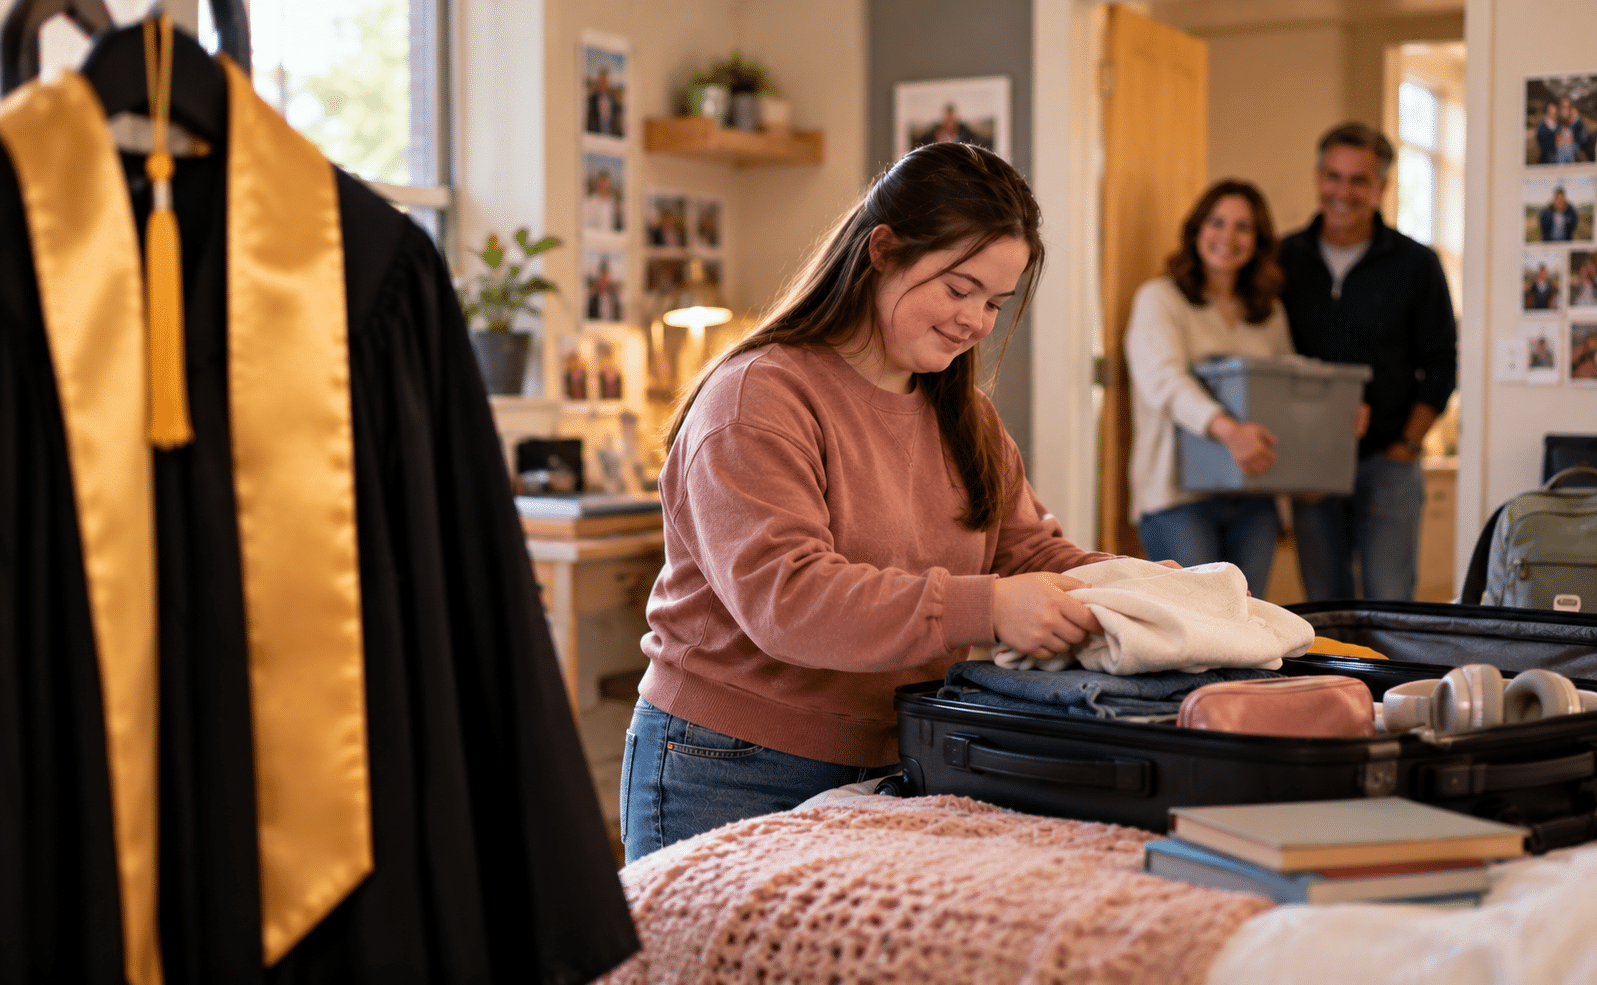
In the summer of 2024, 18-year-old Amanda Hanshaw was getting ready to leave her South Lyon, Michigan, home for college.
That fall, she was headed to the University of Cincinnati, where she would join its four-year Transition and Access Program. She had competed in swimming, was working a summer job to earn money for college, and was preparing for dorm life, classes, new friends, and greater independence.
Amanda also has Down syndrome.
And as she prepared for that next chapter, she had another resource behind her: a MiABLE account.
Her parents had learned about ABLE accounts even before Michigan launched its own program. When MiABLE became available, they opened an account for Amanda with a goal that extended well beyond college: helping give their daughter financial resources that could support greater independence throughout her life.
Amanda’s story is a fitting one to revisit during Down Syndrome Awareness Month because it reminds us of something that can sometimes get lost in conversations about disability:
A child with Down syndrome grows up.
College may be part of that future. So, might employment, relationships, community life, earning and managing money, or living with varying degrees of independence. The path will look different for every person.
And as life changes, so do the questions families face.
WHAT CHANGES WHEN A CHILD WITH DOWN SYNDROME BECOMES AN ADULT?
A birthday does not suddenly change a family’s relationship. Legally, however, adulthood matters.
Having Down syndrome does not automatically mean that parents continue making every financial, healthcare, or personal decision for their adult child. Nor does the diagnosis itself mean guardianship is automatically necessary.
The appropriate level of assistance depends on the individual.
Some adults with Down syndrome may make many decisions independently while receiving help in certain areas. Others may require more extensive support. What someone needs at 18 may also be different from what they need at 30, 40, or 50.
That is why the better question is not, “What does someone with Down syndrome need?”
It is, “What does this person need?”
This is also where legal guidance can become useful. Rather than beginning with the assumption that a family needs one particular document or court proceeding, an attorney can help identify which decisions actually need support and which legal tools may fit the individual’s circumstances.
For families working with Estate Planning & Elder Law Services, P.C., that conversation can include how adulthood changes a parent’s legal role, what authority may or may not already exist, and how available estate planning and decision-making tools fit the person’s actual abilities and needs.
Independence and support do not have to be opposites.
WHAT HAPPENS WHEN MOM AND DAD CAN’T ALWAYS STEP IN?
Parents often carry an extraordinary amount of information without realizing it.
They know the doctors. The routines. The medications. The transportation schedule. The people their son or daughter trusts. What causes anxiety. What makes a bad day better. How much help is needed with money. What independence looks like for that particular person.
Eventually, families have to consider how that knowledge and support will continue when parents are no longer managing everything.
Money is part of that conversation, but it is not the whole conversation.
Who will understand the person’s life? Who will help with healthcare when needed? Who will stay connected? Who will notice when something is wrong? Who will understand not only what money is available, but what that money was intended to make possible?
A trust can hold assets.
It cannot, by itself, hold everything Mom or Dad knows.
That is why our conversations with families should go beyond asking who inherits what. The people selected to serve as trustee, agent, or in other important roles can matter just as much as the documents themselves. Those choices should make sense not only legally, but practically for the person whose life the arrangement is meant to support.
HOW SHOULD AN INHERITANCE BE LEFT TO SOMEONE WITH DOWN SYNDROME?
For some families, this is where good intentions can become complicated.
Some adults with Down syndrome receive means-tested government benefits such as Supplemental Security Income (SSI) or Medicaid. Depending on the person’s circumstances, receiving assets outright can affect eligibility for programs that impose financial limits.
That means how an inheritance is left can matter just as much as how much is left.
A third-party special needs trust may allow parents, grandparents, or others to set aside assets for a person with a disability while having those assets managed under trust terms designed to take applicable benefit rules into account.
There are also first-party special needs trusts, which involve assets belonging to the person with a disability and are subject to different requirements.
But creating a trust is only part of the picture.
Parents might establish a carefully drafted special needs trust while a grandparent’s will leaves money directly to their grandchild. A life insurance policy or retirement account could name the individual directly even though the rest of the family’s arrangements were designed differently.
One uncoordinated inheritance can change the picture.
BENEFITS MATTER. SO DOES THE LIFE BEYOND THEM.
It is easy for conversations about disability and money to become entirely about preserving benefits.
Those benefits can be extremely important. But the person receiving them still has a life to live.
There may be housing costs, transportation, education, employment support, healthcare, technology, personal assistance, and countless other expenses associated with greater independence and quality of life.
That brings us back to Amanda.
Her ABLE account offered her family a way to save toward qualified expenses associated with the life she was beginning to build.
Michigan’s MiABLE Disability Savings Program is the state’s version of an ABLE account. It allows eligible people with disabilities to save and invest for qualified disability expenses while receiving special treatment under certain public-benefit and tax rules.
But MiABLE is not only for people with Down syndrome.
People with intellectual and developmental disabilities, physical disabilities, blindness, neurological conditions, and many other disabilities may potentially qualify if they satisfy the eligibility requirements.
And since Amanda began college in 2024, one of the most important ABLE eligibility rules has changed.
WHO CAN QUALIFY FOR MiABLE IN 2026?
Beginning January 1, 2026, the federal age-of-onset requirement for ABLE eligibility expanded from disability beginning before age 26 to before age 46.
In Michigan, an individual may be eligible if the disability or blindness began before age 46 and the person satisfies the applicable Social Security eligibility or disability-certification requirements.
The change is significant because ABLE accounts are no longer limited to people whose qualifying disability began relatively early in life. Someone whose qualifying disability began in their 30s or early 40s may now potentially meet the age requirement.
That could include people living with many different qualifying disabilities, not only developmental disabilities present from childhood.
A diagnosis alone, however, should not be assumed to establish eligibility. The individual must still satisfy MiABLE’s requirements.
WHAT CAN A MiABLE ACCOUNT ACTUALLY PAY FOR?
MiABLE funds can be used for a broad range of qualified disability expenses related to maintaining or improving the account owner’s health, independence, or quality of life.
Those expenses can include education, housing, transportation, healthcare and wellness, employment training and support, assistive technology, personal support services, legal fees, and financial management.
For 2026, the general annual MiABLE contribution limit is $20,000.
An account owner who earns income may also be eligible to contribute an additional amount from earnings. MiABLE currently lists that additional 2026 amount as up to $15,650, subject to program requirements.
For a person with Down syndrome who works, studies, or is becoming more involved in managing everyday finances, an ABLE account can therefore be more than a place where family members put money aside. Depending on the individual’s circumstances, it can become one of the tools supporting greater financial participation and independence.
WHAT HAPPENS TO SSI AND MEDICAID?
ABLE accounts can be particularly important for some people receiving means-tested benefits because funds in the account receive special treatment under certain benefit rules.
For SSI purposes, the Social Security Administration generally excludes up to and including $100,000 in an ABLE account from countable resources.
If an ABLE balance above $100,000 causes an individual to exceed the applicable SSI resource limit, SSI cash payments can be suspended. Under special ABLE rules, Medicaid can continue when the excess resources causing the suspension are attributable to the ABLE account and the individual remains otherwise eligible.
That does not mean ABLE money comes without rules. How funds are used, when distributions are made, and which benefits an individual receives can all matter.
Families should therefore understand how MiABLE interacts with the person’s particular circumstances rather than assuming that opening an account solves every financial issue.
MiABLE OR A SPECIAL NEEDS TRUST?
Sometimes the answer may be both.
An MiABLE account and a special needs trust can serve different purposes.
A third-party special needs trust may provide a structure for a larger inheritance or other assets parents and relatives want available for someone over many years. A MiABLE account may provide greater flexibility for qualified disability expenses and, depending on the individual, an opportunity to participate more directly in managing some of their own money.
For one adult with Down syndrome, financial independence might mean handling an account largely on their own. For another, it might mean making choices with assistance. Someone else may need considerably more support.
There is no single version of independence, just as there is no single experience of Down syndrome.
DOWN SYNDROME AWARENESS SHOULD INCLUDE THE WHOLE LIFE
In 2024, Amanda was 18 and standing at the beginning of adulthood.
Her story matters because Down Syndrome Awareness Month should not stop at childhood.
People with Down syndrome grow up. They work. They learn. They form relationships. They develop goals and preferences. They make choices. They may seek greater independence. Their abilities, circumstances, and support needs can continue changing throughout their lives.
The questions families ask should grow with them.
What kind of support will this person need? What can they manage independently? Where might they live? Who will remain part of their life? How should an inheritance reach them? Could MiABLE provide useful flexibility? Would a special needs trust make sense? And who will understand all of this when the people who have always been there can no longer handle everything?
Down Syndrome Awareness Month reminds us to see the person rather than the diagnosis.
Their future deserves the same perspective.
If someone you love has Down syndrome or another disability, Estate Planning & Elder Law Services, P.C. can help you understand how special needs trusts, beneficiary designations, MiABLE accounts, and other estate planning tools may work together to support the life ahead.
Call (888) PLAN-050 or email info@formyplan.com to start the conversation.